When partners disagree on selling, options include buyouts, retirement deeds, or full dissolution in the UK. This is because not all partners of the accountancy practice are interested in change at the same time. One partner may want retirement now, while another prefers continued business growth instead.
This is one of the most frequent objections in a practice sale. To put it briefly, one objection doesn’t need to cancel all other possibilities. Your partnership agreement, the laws of the UK, and your valuation will determine your true options.
In such cases, Arbitrage Advisory assists accountancy practice owners in exploring their possibilities for sales and structured exits. In this guide, you will see what happens when partners have different intentions.
What happens when partners disagree on selling a practice?
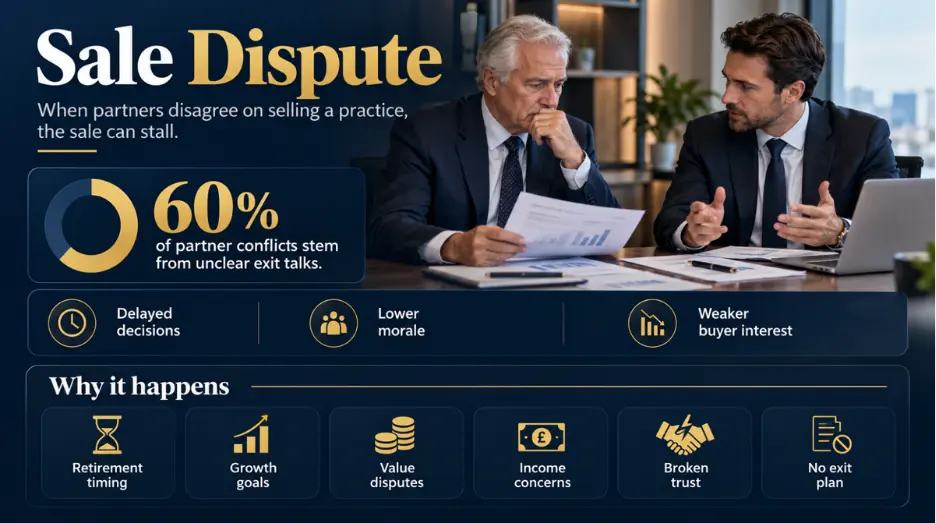
Partners’ views on exit are often split due to age or risk views inside a firm. One partner is ready to retire or move on. The other partner wants to keep growing the firm. This gap can stall decisions, lower staff morale, and weaken buyer interest in the firm.
About 60% of partner conflicts trace back to unclear exit talks at the start of the firm. This creates real tension around selling an accountancy practice with business partner decisions.
Common Reasons Partners Disagree Over a Sale
Partners rarely disagree just for the sake of it. Most conflicts come from real, practical worries. Below are the top reasons partner disagreement in practice sale situations happens:
- One partner is close to retirement age.
- The other partner feels the firm still has growth left.
- The partners have differences on the value of the practice.
- One of the partners may lose their source of income.
- There is no trust between the partners.
- No clear exit plan was ever written down.
Can you sell accountancy practice if your partner disagrees?
No one solution fits all types of partnerships. There could be provisions in your agreement that pertain to sales, exits, transfers, and decisions. The UK government has also advised looking into partnership agreements before any sale of interests. It follows that the partners should be well-versed in their agreements before making any big decisions.
What Does Your Partnership Agreement Say About Selling?
The partnership agreement should be your first point of reference. Most times, it defines what happens next. There are plenty of companies that sign this contract and immediately disregard it. By reviewing it, you’ll prevent months of hassle and legal costs.
Government regulations indicate that an agreement can include terms that apply in connection with sales of interest in the entity. The terms can be very helpful in case the partners have diverse intentions. Reviewing the older agreement before making any sale may be helpful.
What should your partnership agreement say about practice exits?
Your partnership agreement should explain how partners can leave the business. It should also explain what happens when ownership changes between partners. Look for rules covering retirement, transfers, valuation, voting, and dispute handling.
What Is a Partnership Agreement Exit Clause?
A partnership agreement exit clause in the accountancy section explains how a partner can leave. It may cover notice periods and valuation rules. Some agreements also list steps for a forced exit. This clause protects both the leaving partner and the firm.
What If There Is No Exit Clause at All?
Many older partnerships never wrote a clear exit clause. This leaves partners stuck without clear rules to follow. In this case, UK partnership law usually fills the gap. A solicitor should always review your specific situation first.
Which clauses matter most when a partner wants to exit?
The buy-sell clauses indicate how the stock should be sold and who will have priority in buying it. The pricing formula in the contract will fix one approach and thus end long arguments. Deadlock clauses offer a strategy in case partners disagree on selling or merging.
What Rights Does a Minority Partner Have?
Minority partner rules and sale rules protect small owners from being treated unfairly. A minority partner is not someone you can ignore when a sale happens. In many cases, they are owed a fair value for what they own. You should really talk to a lawyer before any final call on the deal.
Can You Force the Sale of Accounting Practice in the UK?
Yes, but only under certain legal conditions. The forced sale of accounting practice in the UK is not simple. Courts usually try to avoid forcing a full sale. They often prefer a partner buyout instead. This keeps the firm running and protects client ties.
When Does Dissolving the Partnership Become the Only Option?
At times, the parties may not come to any terms. In such cases, dissolution of the partnership for the accountancy business in the UK is the ultimate solution. This takes place when mediation and legal negotiations do not work out.
What options exist when one partner wants to leave?
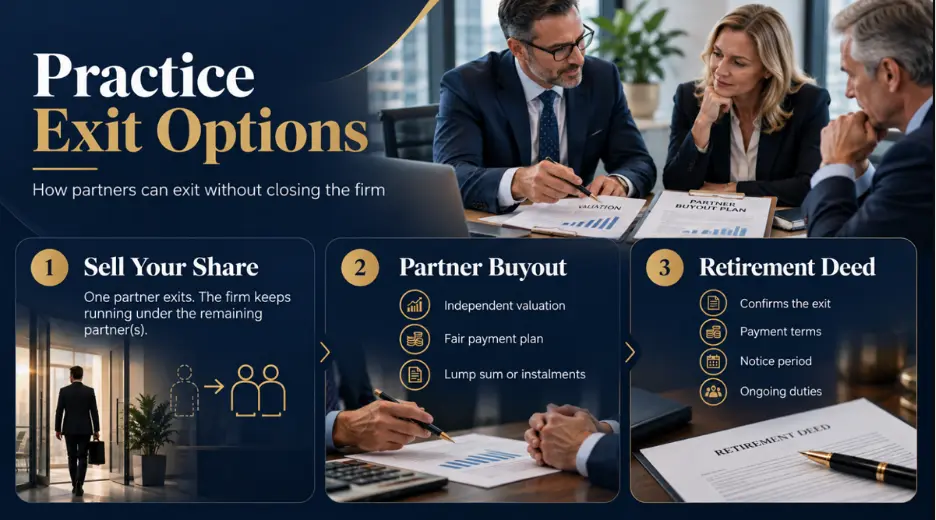
A full sale is only one option for partners. Another choice is selling one partner’s share to the other. The remaining partners can then keep running the firm. A partial sale can also free up cash without ending the firm. Some partners may choose a slow retirement with planned handovers. Others may look at merging with another firm that fits well.
Can You Sell Just Your Share of an Accountancy Practice?
Yes, partial exits are common and often work well. Selling my share of accountancy practice lets one partner leave quietly. The firm keeps running under the remaining partner or partners. This avoids the stress of closing the whole firm down.
How Does Buying Out a Reluctant Partner Work?
Buying a reluctant business partner starts with an independent valuation report. Then both sides agree on a fair payment plan. Payments can be made in one lump sum. They can also be spread out over several years.
What Is a Deed of Retirement in Accountancy?
A deed of retirement in an accountancy partnership formally ends one partner’s role. It confirms they are leaving and sets the final terms. This includes payment amounts, notice periods, and any ongoing duties. Every retiring partner should sign this with legal help.
What is the difference between selling shares vs. selling the whole business?
Selling an accountancy practice with a business partner can involve different ownership and exit routes. Review the differences between selling shares and transferring the entire practice:
| Aspect | Selling Your Share | Selling the Whole Practice |
| Who exits | One partner exits while others may continue | All owners usually exit through the transaction |
| Practice status | The practice may continue with remaining owners | Ownership transfers to the buyer |
| Typical buyer | Existing partners or another agreed buyer | External buyer, group, or another practice |
| Valuation | Value depends on the interest being transferred | Value reflects the overall practice being sold |
| Client impact | Clients may experience limited changes | Clients may face wider changes after ownership transfer |
| Complexity | May involve fewer transaction steps | Usually involves broader legal and client considerations |
| Common use | One partner wants to leave while others remain | Owners want to exit the practice together |
What Is the Best Exit Strategy for a Multi-Partner Practice?
This may not be the case in all firms. An ideal exit strategy for an accounting partnership will depend on personal objectives.
- Full sale: Both partners exit, and the firm changes hands.
- Partial buyout: One partner leaves while the other stays.
- Phased exit: A partner steps back slowly over time.
- Merger: The firm joins a larger, matching practice instead.
How Do You Value an Accountancy Practice Before a Sale?
Getting the numbers right avoids future partner arguments completely. Most UK firms are valued using a fee multiple method. This means a multiple yearly recurring fee income.
| Valuation Factor | Typical UK Range |
| Recurring fee income multiple | 0.8x to 1.3x annual fees |
| Client retention rate needed | Above 85 percent is strong |
| Average deal completion time | 3 to 6 months |
| Staff retention after sale | Often 70 to 90 percent |
What are the risks of selling accountancy practices?
A prepared sale may experience some difficulties during the negotiations and the completion process. Partners must also be aware of the TUPE regulations when selling or buying an accountancy practice in case of transferring employees through a business transaction. Below are some major risks that you should consider.
- Client Loss: When communication skills fail at the point of sale, fearful clients tend to move towards other companies. The longer the period of indecision, the more clients lose trust in their accountant.
- Deal Failure: Any financial or dispute-related issues can ruin an almost completed deal. Lack of appropriate insurance documents can also prevent closing a deal shortly before completion.
- Hidden Liability: Problems from past taxes or client complaints can surface after the sale is completed. Such problems may end up becoming a ground for litigation against the seller.
- Insurance Issues: Inappropriate professional insurance will prevent the sale process. Sellers without appropriate run-off insurance will be susceptible to future client claims.
- Legal Errors: Not getting client consent or missing a filing can cause legal pain later. These errors can end in fines or complaints, or a sale that is cancelled.
What PII issues arise when selling or splitting an accountancy practice?
Insurance needs careful attention when partners sell, split, or transfer practice ownership. Explore the PII table below before agreeing to any ownership transfer terms:
| PII Issue | What It Means |
| Cover Gaps | Old and new policies may leave gaps between coverage periods. |
| Run-Off Cover | Exiting partners may need cover for work completed before leaving. |
| Risk Reassessment | New owners, services, or clients may increase insurance costs. |
| Claims History | Past claims can affect premiums, limits, or insurer terms. |
| Merger Differences | Different cover levels can create gaps after firms merge. |
| Partner Changes | Insurers should know when partners join or leave the practice. |
| Past Work | Responsibility for claims from old work should remain clearly defined. |
| Buyer Conditions | Buyers or lenders may require specific PII cover before completion. |
How should PII be handled in a partial sale or buyout?
In partial deals, both sides must agree on who holds cover for old and new work. Policies may need updates to reflect the new partner list and risk level. Write down all changes clearly, and share proof with the buyer, seller, and legal teams early.
How does dissolving an accountancy partnership work in the UK?
Dissolving an accountancy partnership in the UK means closing the firm and sharing what remains. This is usually the last choice because a sale or buyout may keep more value. Clients may leave, staff may quit, and the firm’s goodwill may fall low.
A practical checklist before partners discusses selling their practice
Use this checklist before contacting buyers or beginning formal negotiations.
| Area | What partners should check before moving forward. |
| Agreement | Review ownership rules and exit terms before talking to any buyer. |
| Value | Agree how the practice value will be assessed between partners. |
| Timing | Discuss retirement plans and the best timing before marketing starts |
| Clients | Review engagement terms and plan careful client communication during transitions. |
| Insurance | Check current cover and any run-off plans before closing. |
| Staff | Think about staff duties and explain changes clearly when needed |
| Buyers | Decide what type of buyer could suit the practice. |
| Advice | Use legal, tax, and value advice where you need it. |
How Can a Practice Sale Broker Help Resolve Disagreements?
An experienced accountancy practice sale broker in the UK takes emotion out of hard talks. Brokers give an outside, neutral view on true value. They also handle buyer contact and protect private details. This keeps daily work steady while a deal comes together.
Is it legally possible to sell only my share of the practice?
Yes, in some cases, if your agreement’s exit clause allows a share transfer. But buyers for small shares are rare, and the price often drops for lack of full control. Many firms prefer a full buyout by the remaining partners instead of bringing in a new share owner.
FAQs
Tax may apply to money you get when you sell your practice or share. Your own situation and deal structure can change the final tax you owe. A tax adviser should review the deal before you agree to final terms
A buyer may change the practice name based on the deal and business type. This can affect how clients see the firm, staff trust, and future marketing. Partners should talk about a possible name change before signing final terms
Arbitrage Advisory can help you understand sale routes and get ready for buyer talks. Our specialist focus gives clearer planning when partners want different outcomes. Owners can explore their options before picking the right path for their practice.
Client records need careful handling when ownership changes between parties. Owners should follow the right rules and agreed terms when moving client data. Planning this early can cut confusion and protect key client ties.
Conclusion
A clash with your partner does not mean the practice must shut down. It also does not mean that one partner must give up their plans. You can still find a fair path once you know your options.
At Arbitrage Advisory, we work as a specialist boutique for accountancy practice brokerage. We review your partnership agreement and give you a reliable valuation for the firm. We also help both partners get on the same page about the way ahead.
Then we look for serious buyers who pay well for solid and well-managed practices. Book a confidential call with Arbitrage Advisory right now to consider your options. We will help you to make the best out of this difficult situation.