Selling an accountancy practice is not just about turnover. Buyers pay for predictable profit, low risk, and a client base that stays once you leave.
Here’s the thing. If your practice depends a lot on you, buyers notice. If your records are messy, buyers notice that too. The same goes for a practice that leans on just a few big clients. Buyers spot these risks fast, and they use them to push the price down.
The good news? Most of this can be fixed. You just need to start early. This guide covers what really helps to increase accountancy practice value. It also covers what quietly drags value down. And what to fix first, based on your own timeline.
What Makes an Accountancy Practice More Valuable to Buyers?
A practice becomes more valuable when it makes steady profit and carries less risk. Simple as that.
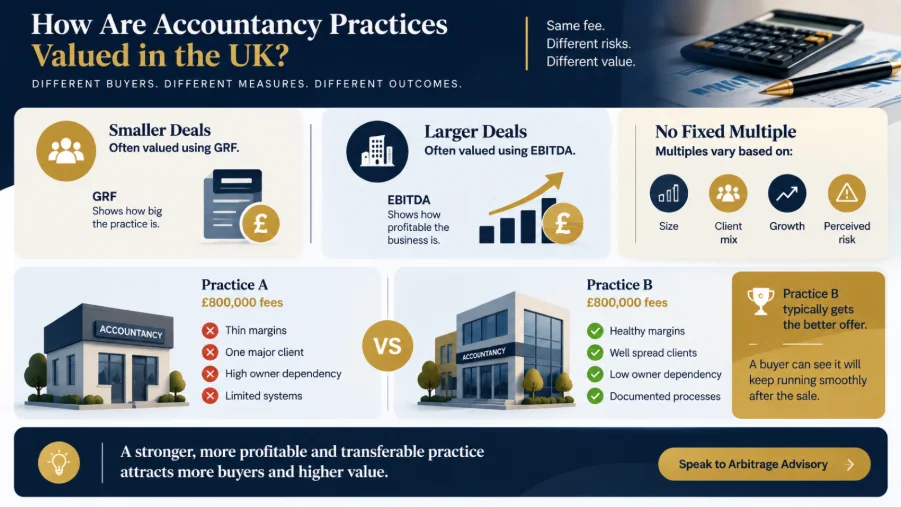
The main accountancy practice valuation factors include GRF and EBITDA. Retention and concentration matter too. So do owner dependency, staff strength, pricing, systems, and compliance. Strong fee income does not save you if your margins are thin. Buyers will still mark that down. The same goes for a profitable practice. If it only works because of the owner’s own relationships, that’s a problem too.
Assess What Is Reducing Your Practice’s Value
Before you chase new turnover, find out where value is leaking first. Growth built on top of existing gaps just makes those gaps bigger.
Review revenue quality, profitability, and owner dependency together. Add concentration, staff risk, pricing, debtors, WIP, and compliance to that list too. Look at the full picture, not just one issue at a time.
Then focus on your fixes. Rank them by buyer risk first. Then think about financial impact. And how long each one will take to sort out.
Reduce Owner Dependency Before You Sell
Owner dependency is one of the greatest risks to an accountancy practice’s value. When clients trust only you, buyers may expect some to leave after you step back and factor that risk into a lower offer, which is exactly why it tops our list of mistakes that kill accountancy practice sale value.
Signs Your Practice Relies Too Heavily on You
- Clients contact you directly instead of speaking with the wider team.
- You personally approve or sign off most of the work.
- A two-week holiday would disrupt day-to-day operations.
If any of these signs apply, reduce the dependency before going to market. Bring senior staff into client meetings, delegate genuine decision-making authority rather than routine tasks, and document key processes so essential knowledge does not remain solely with you.
Improve Recurring Revenue, Pricing, and Client Quality
Recurring fees accountancy practice valuation is strongest where the work is predictable and reasonably priced. Bookkeeping and payroll recur often, but they carry lower margin.
Advisory retainers work differently. They carry stronger margins and build deeper relationships. Project work, on the other hand, adds turnover but rarely adds lasting value.
Not all recurring fees are equal. Two clients might pay you the same fee. But one might take far more of your time. And pay late too. That fee is simply not worth the same.
More turnover does not always mean more value. That’s a trap many owners fall into. Labour costs eat into the margin quietly. So, do partner time and write offs.
So, should you remove unprofitable clients before selling? It depends. Cutting them can lift your margins. But it also lowers your headline GRF, so weigh this against your concentration risk first.
What about raising fees before selling? Sudden increases right before a sale can trigger client attrition. That’s risky timing. A planned repricing plan, phased over twelve to eighteen months, works far better.
Reduce Client Concentration and Retention Risk
Picture this. One client, or a small linked group, brings in a huge share of your fees. If you lost them, would revenue take a serious hit? If so, buyers see that as concentrated risk.
Client concentration accountancy practice valuation concerns often lead to lower offers. Sometimes buyers ask for extra protection in the deal terms instead.
So how do you measure this? Check your largest client’s share of fees first. Then look at your top five, and your top ten. Also check whether a few clients sit in one sector. There is no universal safe percent here, so judge it against your own client base.
Historical data proves retention far better than assurances ever could. Show your tenure, your churn over a few years, and your fee stability. Spread this across the whole team, not just one partner.
Client retention practice sale risk after completion is often managed a few different ways. Think deferred consideration, retention thresholds, clawback, or earn outs.
Strengthen Your Team and Systems
Staff tenure matters more than owners often realise. So does technical capability and client relationships. Together, these shape how confidently a buyer can picture running the practice without you.
A team that only functions with one key manager create a problem. It’s the same kind of risk as an owner who cannot step back. So cross train your staff. Document duties clearly. Build real management depth before you go to market.
One more thing. Where employees transfer as part of the sale, TUPE protections likely apply, and it’s worth understanding what TUPE means for staff before you get close to completion. Take specific advice on this for your own deal.
Systems matter too. Modern practice management software helps here. So does cloud accounting and a client portal. All three make a practice easier to plug into a buyer’s setup.
What about AI and automation in 2026? Can they increase practice value? Not on its own, no. AI helps when it truly makes work faster and cuts the need for any one person. But it turns into a problem, not a benefit, if governance and data security fall behind.
Clean Up Debtors, WIP, and Financial Records
Aged debtors raise a red flag for buyers. Why? They point to weak billing discipline and slow collections, and buyers read that as risk.
WIP treatment often depends on how the deal gets planned. So, clarify this early with your adviser, rather than guessing.
Before you go to market, tidy up your aged receivables. Clear out old WIP. Update your management accounts. And be ready to explain any unusual adjustments a buyer might spot.
Prepare for Buyer Due Diligence Before the Buyer Starts It
Accountancy practice due diligence often covers a few key areas. Think finances, client data, staff, day to day work, and compliance history.
A useful due diligence checklist practice sale has verified accounts and engagement letters. Add AML and CDD records, GDPR practices, and employment records to that list too.
ICAEW rules on selling practice centre on a few core ideas. Client privacy matters. So does giving clients a genuine choice about the new owner. A responsible handover matters too. That said, exact rules depend on your own situation. Confirm current guidance with ICAEW directly.
Understand How Different Buyers May Value Your Practice
Not every buyer thinks the same way. Another accountancy firm might value cultural fit and local relationships most. A bigger buyer often cares more about scale and systems integration.
A private equity backed buyer often focuses on EBITDA and growth potential instead. An internal buyout may focus on continuity over the highest headline price.
The takeaway? Each buyer type can mean a different valuation method, and different deal terms too.
Asset Sale vs Share Sale: Why Structure Matters
Asset sale vs. share sale practice choices shape tax, liability, and risk for both sides. So, what’s the difference?
An asset sale means selling specific assets and client relationships. The company itself stays with the seller. A share sale is different. It means selling ownership of the whole company, including its history and liabilities.
Neither option is simply the better one. It depends on liability, tax treatment, contracts, and what the buyer prefers. Take deal specific advice before you commit to either route.
Earn-Out vs Lump Sum: Compare the Real Value of the Offer
An earn out pays part of the price later. That payment often depends on the practice hitting agreed targets after completion. Clawback works alongside this. It lets a buyer reduce that later payment if clients leave, or targets get missed.
Earn-out vs lump sum practice sale choices come down to certainty versus upside. A lower price with more cash up front can beat a bigger figure loaded with conditions. It all depends on how much risk you want to hold once you walk away, and it’s often shaped by how the buyer themselves is funding the acquisition in the first place.
Before accepting deferred consideration, check a few things carefully. What are the payment triggers? How are figures calculated? How much control do you keep over clients during the earn out period? And how are lost or new clients treated?
Calculate What You May Really Keep from the Sale
Cost of selling accountancy practice often has valuation fees and advisory fees. Add broker fees where used. Solicitor and tax adviser costs come into it too. These costs vary by size and complexity. So, avoid guessing that a fixed percent applies to your deal.
Capital gains tax on practice sale proceeds depends on how the deal gets planned. Business Asset Disposal Relief can reduce your Capital Gains Tax rate on qualifying disposals. But the rate has risen in recent years. From 6 April 2026, it sits higher than in the previous two tax years, a change we break down fully in our guide to Business Asset Disposal Relief and the 18% rate rise. Confirm the current rate with a tax adviser before guessing anything applies to you.
Net proceeds matter more than the headline price, always. Start with the headline consideration. Subtract deal costs, tax, and the risk attached to any conditional payments. What’s left is a far more realistic picture of what you will really keep.
What Should You Focus on if You Want to Sell Within 12 Months?
If time is short, focus your energy carefully. Start with a realistic valuation and accurate financials. Then tackle compliance problems and owner dependency, where you can.
Fix major concentration risks next. Secure your key staff. Clean up debtors and WIP. And keep sight of your net proceeds throughout, following the same practical order set out in ours step-by-step guide to maximising your sale price.
The goal here is simple. Reduce the concerns buyers will really raise. Don’t try to rebuild the whole practice in a few months.
Making the Right Choices for Your Situation
There is no single fix for every practice. It really depends on your timeline.
Selling a few years out? Focus on owner dependency, pricing, profitability, client quality, and succession, an area covered further in our guide to succession planning options for accountants. Selling within a year? Focus on an honest valuation, accurate records, compliance readiness, and concentration risk instead.
Already weighing buyer offers? Look past the headline number. Study buyer fit, payment structure, clawback, and tax instead. These details matter more than they seem.
The strongest practice is the most valuable one too. It’s the one that can keep serving clients well after the seller steps away.
Not sure which issues could reduce your practice’s value? Speak with Arbitrage Advisory before you go to market. A professional pre-sale valuation and review can help. It flags value gaps and buyer risks early. It also gives you a clearer strategy for the sale ahead.
FAQs
Reduce owner dependency. Improve profitability, not just turnover. Strengthen retention and clean up your financial and compliance records.
Smaller deals are often priced against GRF. Larger or PE backed deals lean more on EBITDA. No fixed multiple applies to every practice.
Ideally, two to three years. Owner dependency and profitability issues take real time to fix well. That said, even six to twelve months of focused work can still help.
Not always. But expert support often secures better terms. It can also spot risks in due diligence that owners miss on their own.